
Sole Trader or Limited Company: The Old Rule of Thumb Stopped Working
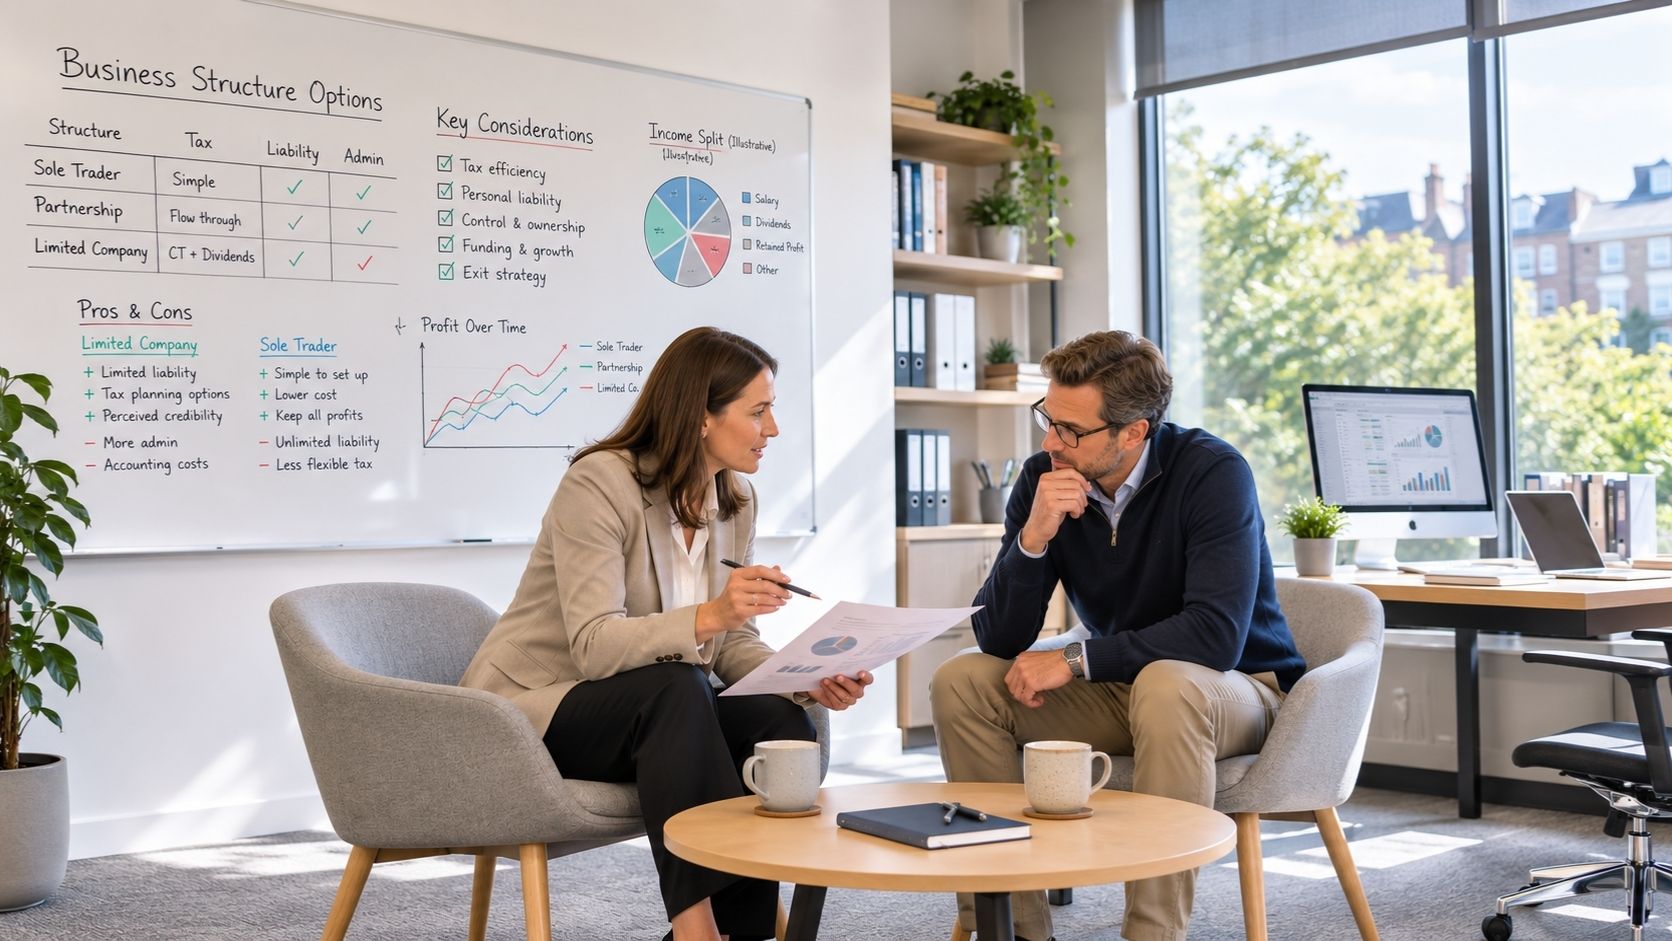
For years, one of the most familiar pieces of small-business tax advice was simple: once your profits reached a certain level, it was time to incorporate.
The tax saving was often large enough to justify the additional administration, and advisers could usually demonstrate the benefit with a relatively straightforward salary-and-dividend calculation.
That rule of thumb has become much less reliable.
Dividend tax rates increased on 6 April 2026. Corporation Tax is no longer a single low rate, employer National Insurance has become more expensive, and the dividend allowance has been reduced substantially over recent years.
For many owner-managed businesses where most or all profits are extracted each year, the tax advantage of operating through a limited company has narrowed materially.
The question is therefore no longer simply:
"At what profit should I incorporate?"
It is:
"What would a limited company actually do for me?"
What changed?
Dividend tax increased in April 2026
From 6 April 2026, the ordinary and upper dividend tax rates increased by two percentage points.
| Band | Until 5 April 2026 | From 6 April 2026 |
|---|---|---|
| Basic / ordinary rate | 8.75% | 10.75% |
| Higher / upper rate | 33.75% | 35.75% |
| Additional rate | 39.35% | 39.35% |
A two-percentage-point increase may not sound dramatic.
But for an owner-manager extracting a substantial part of the company's profits as dividends every year, it directly increases the second layer of tax paid after Corporation Tax.
The dividend allowance is now only £500
The tax-free dividend allowance is £500 for 2026/27.
That means that, once the allowance and any available Personal Allowance have been used, almost all dividends received by a typical owner-manager are potentially taxable.
A few years ago, the dividend allowance sheltered a much larger amount.
It no longer plays a significant role in most incorporation calculations.
Corporation Tax is not simply 19%
The small profits rate is generally 19% where taxable profits are £50,000 or less.
The main rate is 25% where profits exceed £250,000, with marginal relief operating between the two.
These thresholds can be reduced where the company has associated companies or a short accounting period.
So a company earning £80,000 does not simply pay Corporation Tax at 19%.
That matters when comparing company profits with the Income Tax and National Insurance payable by a sole trader.
Employment Allowance does not automatically help a one-person company
The Employment Allowance can reduce an eligible employer's National Insurance liability by up to £10,500 in 2026/27.
But there is an important exclusion for small owner-managed companies.
A company generally cannot claim the allowance where a single director is the only employee whose earnings give rise to employer Class 1 National Insurance.
This rule is not new, but it matters more now that employer National Insurance is charged at 15% above a Secondary Threshold of only £5,000 a year.
That means the salary element of a one-person company's salary-and-dividend strategy can itself create a meaningful employer National Insurance cost.
So where does the maths land?
There is no reliable universal profit level at which a sole trader should become a limited company.
A comparison depends on assumptions including:
- how much salary the director takes;
- how much profit is distributed as dividends;
- how much is retained in the company;
- other personal income;
- pension contributions;
- Employment Allowance eligibility;
- whether the company has associated companies;
- the owner's future plans; and
- in some cases, the ownership structure.
This explains why published comparisons can produce very different crossover points.
For many owner-managed businesses that withdraw nearly all profits each year, incorporation produces a much smaller tax advantage than it once did — and in some cases there may be no tax advantage at all.
But that does not mean limited companies have stopped making sense.
It means tax alone is no longer a sufficient rule of thumb.
The biggest variable: how much profit do you take out?
This often changes the answer more than the headline profit figure.
If you take almost everything out
A company first pays Corporation Tax on its taxable profits.
If the remaining profit is then distributed to you as dividends, you may pay dividend tax personally as well.
That creates two layers of tax.
For an owner who needs to withdraw nearly everything the business earns to fund personal living costs, the traditional tax advantage of incorporation may therefore be relatively small.
If you leave money in the company
The calculation changes.
A company can retain post-Corporation-Tax profits for future investment, working capital or later extraction.
Personal dividend tax does not generally arise simply because profits remain inside the company.
A sole trader does not have that option for Income Tax purposes: they are taxed on the taxable profit of the trade whether they withdraw the cash personally or leave it in the business bank account.
For a growing business that can retain a meaningful part of its profits, incorporation can therefore remain attractive.
Reasons to incorporate that have nothing to do with tax
As the pure tax advantage becomes less decisive, the commercial reasons for incorporating matter more.
Limited liability
A sole trader and their business are legally the same person.
Business debts are therefore generally the individual's debts.
A limited company is a separate legal entity. In normal circumstances, shareholders' exposure is limited.
That protection is not absolute. Directors can still have personal exposure where, for example, they give personal guarantees, breach their duties or become personally liable under insolvency or other laws.
But for a business taking on employees, premises, borrowing or substantial contractual obligations, the separation between the individual and the business can be a major reason to incorporate.
Who you can work with
Some larger organisations prefer or require suppliers to operate through incorporated entities.
That can arise through procurement policies, insurance requirements or supplier onboarding procedures.
If being a sole trader prevents you from bidding for important work, a small tax difference becomes secondary.
Credibility and perception
Whether it should matter or not, some customers, suppliers and lenders perceive a limited company as a more established business structure.
In some industries this makes little difference.
In others, it affects supplier approval, tenders or commercial negotiations.
Raising equity
You cannot sell shares in a sole trade.
If you expect to raise outside equity or want an ownership structure in which interests can be issued or transferred over time, a limited company is usually more suitable.
That does not mean a company is the only way to bring another person into a business — ordinary partnerships and LLPs are also available — but a company provides a familiar framework for equity ownership.
Pensions
Employer pension contributions can be particularly valuable for owner-managed companies.
A company can normally obtain Corporation Tax relief for genuine employer pension contributions made as part of a director's remuneration package, subject to the usual wholly-and-exclusively test.
Unlike personal pension contributions, employer contributions are not restricted by the director's relevant earnings.
They do, however, count towards the individual's pension annual allowance, which is £60,000 for most people in 2026/27 and may be lower in some circumstances.
For an owner who wants to build significant pension provision rather than extract all profits personally, this can materially affect the company-versus-sole-trader calculation.
Protecting the company name
Incorporation registers a legal company name with Companies House.
Another company generally cannot register the same name.
That is useful, but it should not be confused with trade mark protection. Registering a company does not, by itself, give you exclusive rights to use the brand or prevent another business from using a similar trading name.
Reasons to remain a sole trader
Simplicity has real value
A sole trader normally has a simpler compliance structure.
A limited company must deal with:
- statutory annual accounts;
- a Company Tax Return;
- Companies House filings, including the confirmation statement;
- company records and directors' duties; and
- payroll where a director or employees are paid salary.
The director may also need to submit a personal Self Assessment tax return, depending on dividends and other income.
This means more administration and, where professional support is used, higher annual fees.
At modest profit levels, those additional costs can absorb much of a small tax saving.
Business money is easier to access
A sole trader's business profit belongs to the individual.
A company's money belongs to the company.
An owner-manager must therefore extract company funds properly — for example through salary, dividends, expense reimbursement, repayment of money previously lent to the company or a properly recorded director's loan.
Dividends also require sufficient distributable reserves and appropriate company records.
Taking money informally can create an overdrawn director's loan account.
Depending on the amount borrowed, the interest charged and how long it remains outstanding, this can lead to additional company and personal tax consequences.
This distinction between your money and the company's money is one of the biggest practical adjustments for people who incorporate after years of trading as sole traders.
There is a public record
A limited company has a public Companies House record.
Filed accounts and information about directors, people with significant control, share capital and certain shareholder details may be publicly accessible.
Some business owners are comfortable with that.
Others prefer the greater privacy associated with operating as a sole trader.
Directors have statutory duties
A company director has legal duties to the company in addition to the commercial responsibilities of running the business.
There are also filing obligations, identity-verification requirements and specific responsibilities where a company experiences financial difficulty.
A limited company may protect shareholders through limited liability, but being a director is not a liability-free role.
The administrative gap is narrowing
Historically, one reason to remain a sole trader was the much lighter record-keeping burden.
Making Tax Digital for Income Tax is narrowing that difference.
Sole traders within MTD now have to maintain digital records and submit quarterly updates to HMRC.
A limited company still has significantly more company-law and accounting obligations, but the gap in day-to-day bookkeeping is smaller than it once was.
If you are already incorporated
This question is not only for people considering whether to form a company.
It can also be worth revisiting if you incorporated several years ago because of a tax comparison that no longer produces the same result.
Suppose you:
- have no employees;
- face little commercial liability;
- do not need a company to win clients;
- take almost all profits out every year; and
- incorporated primarily for tax reasons.
It is reasonable to ask whether the company structure is still earning its keep.
That does not mean simply striking the company off and continuing tomorrow as a sole trader.
Transferring a business out of a company can create tax consequences for both the company and its shareholders.
Depending on the business, issues can include:
- Corporation Tax;
- Capital Gains Tax;
- Income Tax on distributions;
- VAT;
- PAYE;
- transfer of equipment, stock or property;
- contracts and customer relationships; and
- how remaining company cash is extracted.
After transferring the trade, the company may then be struck off, liquidated, kept dormant or used for another purpose.
For that reason, disincorporation should normally be planned rather than treated as a simple Companies House filing.
A structure chosen in 2018 does not have to remain the right structure forever — but unwinding it deserves the same care as setting it up.
How to make the decision
Start with the commercial reasons
Ask first:
- Do I need limited liability?
- Do important customers expect an incorporated supplier?
- Will I need outside investment?
- Do I expect to retain profits?
- Is substantial employer pension funding part of my plan?
A strong answer to one of those questions may be more important than a relatively small tax difference.
Then model what you actually withdraw
Do not compare a theoretical company with a theoretical sole trader.
Model:
- the profit you realistically expect;
- your required personal drawings;
- salary;
- dividends;
- retained profits;
- pension contributions;
- other income; and
- the annual cost of running the company.
That is the calculation that matters.
Do not rely on a universal threshold
There is no reliable rule that says:
"Incorporate once profit reaches £X."
Two businesses earning exactly the same profit can reach different conclusions because their owners need different amounts of cash, have different other income and want different things from the structure.
Remember that the choice is not permanent
Many businesses sensibly start as sole traders and incorporate later.
Others may eventually decide that a company they formed years ago is no longer useful.
The mistake is not choosing one structure or the other.
It is continuing to rely on an old rule of thumb after the tax rates and the business itself have changed.
Not sure whether your structure still fits?
The honest answer to "sole trader or limited company?" in 2026 is that it depends.
Profit matters — but so do the amount you need to withdraw, other income, pensions, liability, customers, investment plans and the cost of running the structure.
If you would like the comparison run using your own figures — including what would change if you incorporated, or what would be involved in moving back to sole trader status — get in touch.
Get in Touch →